Yes, in many cases you can sell while you still own the property, but the sale must close in time to pay or otherwise resolve the mortgage and other liens before the trustee sale changes ownership. If you are asking can I sell my house before foreclosure, the first facts to verify are the scheduled sale date, the official payoff amount, and whether the expected sale proceeds are enough to clear the required debts and closing obligations. A signed purchase contract by itself does not stop a foreclosure auction Utah homeowners are facing. If the expected proceeds are short, lender approval may be needed for a short sale. The earlier you confirm the timeline, the more realistic your options are.
Where You Are in the Utah Foreclosure Timeline Matters
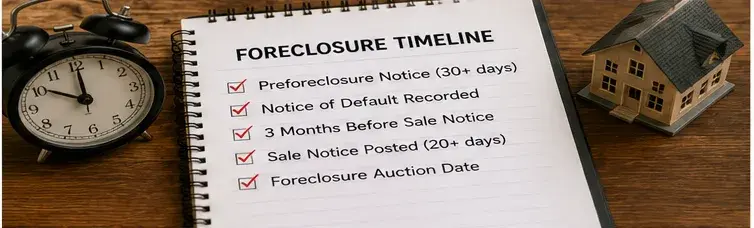
Most Utah residential foreclosures are handled through a nonjudicial trustee sale process. The notices you have received can tell you how much practical time remains, so identify the stage before choosing a sale or loss mitigation option.
| Stage | Key timing | Best immediate action |
| Preforeclosure notice | At least 30 days to cure before notice of default for covered loans | Contact servicer and compare keep or sell options |
| Notice of default recorded | At least 3 months before notice of sale | Request payoff, confirm arrears, review reinstatement |
| Notice of trustee sale | Sale date is scheduled; statutory notice and publication steps apply | Coordinate title, payoff, buyer, or loss mitigation immediately |
Before the Notice of Default
For covered owner occupied residential loans, Utah law requires a preforeclosure notice before a notice of default is recorded. The notice must identify the default, state the cure amount, and give a cure date at least 30 days after the notice is sent. This early stage is a critical time to contact the servicer, ask about foreclosure help Utah programs, and decide whether keeping or selling the property is realistic.
After the Notice of Default Is Recorded
Once the notice of default Utah homeowners receive is recorded, the trustee cannot immediately schedule the sale. Utah law requires at least three months to pass before the trustee gives notice of sale. Record the default date, trustee information, servicer contact, arrears, and a current payoff request. Utah foreclosure laws and the Utah foreclosure reinstatement period make this stage especially important for homeowners who may still be able to cure the default.
After the Notice of Trustee Sale
The notice of trustee sale Utah process identifies the scheduled auction date, time, and place. Utah also requires notice, posting, and publication steps before the sale. Once the trustee sale Utah date is set, the practical window to list, find a buyer, clear title, obtain payoff figures, and close is much shorter. Do not rely on an estimated date. Confirm the current Utah foreclosure sale directly with the trustee or servicer.
How Late Can You Sell Before the Foreclosure Auction?
There is no safe last day that applies to every case. The homeowner must still own the property, and the closing must be able to pay or otherwise resolve the secured debt and required liens before the trustee sale is completed. That is why how late can you sell before foreclosure is mainly a closing and title question, not just a marketing question.
Order a written mortgage payoff before foreclosure sale as early as possible. Give the foreclosure documents to the title or closing professional and ask whether all liens can be cleared by the proposed closing date. Confirm the auction date with the trustee. If more time is needed, ask the servicer or trustee about available postponement or loss mitigation options. Do not assume the auction will wait because you have accepted an offer.
How to Sell a House in Pre Foreclosure
A preforeclosure sale needs a tighter process than an ordinary sale because the closing date has a hard external deadline.
- Confirm the exact trustee sale date and current foreclosure status.
- Request a written mortgage payoff and identify every recorded lien.
- Estimate the home’s realistic as is value and likely net proceeds.
- Choose a sale method that matches the time available.
- Give the title or closing professional the foreclosure notices immediately.
- Make sure payoff funds and required documents can be delivered before the trustee sale.
If you need to sell house fast before foreclosure, speed matters only when the buyer can close and the title can be cleared. A fast promise does not replace proof of funds, payoff coordination, or a workable contract. When learning how to sell a house in pre foreclosure, focus on a realistic close rather than the fastest advertised timeline.
What If the Home Is Worth More Than the Mortgage?
If the expected sale proceeds are enough to pay the official mortgage payoff, other liens, agreed closing costs, and required prorations, a normal sale may let you preserve remaining equity. Compare the likely sale price with the payoff statement, not only the principal balance shown on a monthly mortgage statement.
Equity does not remove the deadline. Buyer financing, inspection issues, title problems, repairs, or a delayed closing can still prevent the transaction from finishing before the auction. Homeowners considering cash home buyers foreclosure Utah options should compare proof of funds, net proceeds, and the exact closing date before choosing a buyer.
What If the Sale Price Will Not Cover the Mortgage?
If the expected proceeds cannot satisfy the mortgage and other required obligations, a short sale may be an option. A short sale is not simply a discounted sale. It requires approval from the mortgage servicer and the loan owner, and other lienholders may also need to cooperate.
Do not assume that listing the home as a short sale automatically stops the foreclosure process. Submit any required loss mitigation package early and keep proof of delivery. A complete application submitted early enough can trigger federal mortgage servicing protections, but approval is not guaranteed. Ask the servicer what foreclosure options Utah borrowers may qualify for and what must happen to postpone or stop the sale.
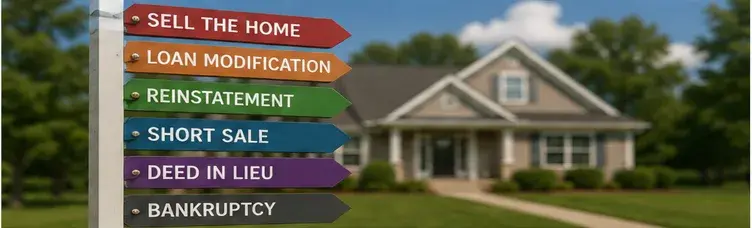
Options That May Help You Keep the Home
Reinstate the Loan
Utah provides a statutory reinstatement right under a trust deed during the three month period after the notice of default is recorded, subject to the statute. Reinstatement generally requires the amount then due, plus applicable enforcement costs and fees, rather than the entire unmatured principal. Request a current reinstatement figure and confirm the deadline if your goal is to avoid foreclosure Utah through curing the default.
Ask About a Loan Modification or Forbearance
A loan modification before foreclosure Utah borrowers receive can change the loan terms if the servicer approves it. Foreclosure forbearance Utah options may temporarily reduce or pause payments, but missed amounts are not automatically erased. Federal servicing rules can provide additional protections for a complete loss mitigation application submitted early enough. The closer the auction is, the less time remains for review, so contact the servicer promptly.
Options If You Are Ready to Leave the Property
Deed in Lieu of Foreclosure
With a deed in lieu of foreclosure Utah arrangement, the homeowner voluntarily transfers ownership to the lender or servicer under an approved agreement. This can avoid a completed trustee sale in some cases, but the lender must agree. Confirm in writing how any deficiency balance, relocation terms, or other obligations will be handled before signing.
Selling to a Cash Buyer
A cash buyer may reduce the time needed for financing and appraisal, which can help when the sale date is close. However, a cash buyer has no special power to stop foreclosure. The transaction still must close, the secured debt must be resolved, and title must transfer before the trustee sale.
If you are considering cash home buyers foreclosure Utah options, compare the net offer, proof of funds, fees, title requirements, contingencies, and written closing date. A cash sale may be practical when time is short, but it is not automatically the best financial result.
Can Bankruptcy Stop a Utah Foreclosure Auction?
A bankruptcy filing generally creates an automatic stay that stops many collection actions, and Chapter 13 can provide a framework for addressing mortgage arrears over time. But bankruptcy is a major legal and financial step. Exceptions apply, creditors can seek relief from the stay, and filing after a completed foreclosure sale may be too late to preserve the property.
Do not use bankruptcy to stop foreclosure Utah proceedings without legal advice about the full consequences. Speak with a qualified bankruptcy attorney before the sale date if bankruptcy is being considered.
Does Utah Give You a Redemption Period After the Trustee Sale?
No general post sale redemption period applies after a completed nonjudicial trustee sale under Utah’s trust deed process. The trustee’s deed transfers the property without a post sale right of redemption. Judicial foreclosure rules can differ, but the common Utah nonjudicial process should not be confused with states that give homeowners a later statutory period to reclaim the property.
This makes the Utah foreclosure redemption period question especially important. If you intend to sell, reinstate, or seek other relief, act before the trustee sale is completed.
What to Do When Your Auction Date Is Already Scheduled
When a foreclosure auction Utah date is already on the calendar, verify facts before making assumptions. Confirm the date, time, place, trustee, and current payoff. Contact the servicer’s designated foreclosure contact immediately. If you are selling, give the title or closing professional all foreclosure documents so payoff and lien work can start at once.
If you are pursuing loss mitigation, submit a complete package as early as possible and keep proof of delivery. If bankruptcy is being considered, get legal advice before the sale. Never rely only on a verbal statement that the auction has been postponed. Confirm any postponement through the trustee, servicer, or another authoritative source.
Frequently Asked Questions
Can you sell a house in foreclosure in Utah?
Yes, while you still own the property and the transaction can close in time to pay or otherwise resolve the secured debt before the trustee sale. A signed contract alone does not stop the auction, so payoff and closing coordination are essential.
How long after a notice of default can a Utah trustee sale happen?
At least three months must pass after the notice of default is recorded before the trustee gives notice of sale. The required sale notice process then follows. The actual auction date should always be confirmed from the trustee’s current records.
Can a loan modification stop a foreclosure auction in Utah?
An approved modification or other written loss mitigation agreement can affect foreclosure activity. Simply applying does not guarantee approval or postponement. Federal servicing protections may apply when a complete application is received early enough before the scheduled sale.
What is the Utah foreclosure reinstatement period?
Utah’s statutory trust deed reinstatement right generally applies during the three month period after the notice of default is recorded, subject to the statute. Ask the servicer or trustee for the current reinstatement amount and deadline.
Is there a redemption period after a Utah trustee sale?
A completed nonjudicial trustee sale transfers the property without a post sale right of redemption under Utah’s trust deed statute. That is why homeowners should not plan on recovering the home through a general redemption period after the auction.
Final Takeaway
If you are asking can I sell my house before foreclosure, the answer can still be yes, but timing controls the value of that option. Confirm the auction date, order a written payoff, identify liens, and find out whether a sale can actually close before ownership changes. If selling does not fit the numbers or timeline, compare reinstatement and available lender relief promptly. Acting early gives you more room to evaluate how to avoid foreclosure Utah without assuming that any single option is guaranteed to stop the sale.