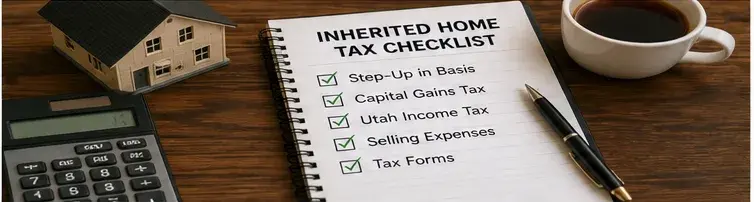
Selling an inherited home can create tax questions even when receiving the property itself did not. Utah does not currently impose an inheritance tax simply because you inherited the home, but a later sale can create federal and Utah income tax consequences if the transaction produces a taxable gain. The capital gains tax on inherited property is usually based on the home’s inherited basis, which is generally tied to fair market value at the date of death, not what the previous owner originally paid. That rule can greatly reduce the taxable gain when a home is sold soon after inheritance. Before selling, understand the basis, valuation records, sale expenses, and tax forms that may apply.
What Taxes Can Apply When You Sell an Inherited Home in Utah?
The main tax issue for most Utah heirs is not a tax on receiving the inheritance. It is whether the later sale creates a taxable capital gain. Federal capital gains tax on inherited property can apply when the amount realized from the sale exceeds the property’s adjusted inherited basis. Utah can also tax taxable income that includes recognized gain under state rules. For taxable years beginning in 2026, Utah’s individual income tax rate is 4.45%, but this is not a separate special capital gains rate.
It helps to separate the possible taxes:
| Tax type | When it may apply | Who generally pays |
| Federal capital gains tax | When the sale creates taxable gain after basis and adjustments | The taxpayer reporting the gain |
| Utah income tax on taxable gain | When recognized gain is included in Utah taxable income | The Utah taxpayer reporting the gain |
| Utah inheritance tax | Not currently imposed for modern inheritances | Not applicable under current Utah rules |
| Federal estate tax | May apply to certain large estates under federal rules | Generally the estate, not a tax created by the later home sale |
The tax consequences of selling inherited house property therefore depend on the sale result and tax basis. Inherited property tax language can be confusing because inheritance, estate administration, and a later sale are different taxable events.
Does Utah Have an Inheritance Tax or Estate Tax?
Utah does not currently impose an inheritance tax. The state’s former inheritance tax was eliminated after December 31, 2004. Utah also does not impose a separate current state estate tax system in the way some states do. Federal estate tax rules remain separate and can apply to qualifying estates.
This distinction matters because inherited house taxes are often discussed as if the heir automatically owes tax when receiving a home. For most Utah homeowners, the more immediate question is what happens when the property is sold and whether the sale creates a taxable gain.
How the Step Up in Basis Can Reduce Tax on an Inherited Home
Basis is the tax starting point used to measure gain or loss. For inherited property, the basis is generally the fair market value of the property on the date of the owner’s death, subject to exceptions and alternate valuation rules. This is commonly called the step up in basis inherited property receives.
The rule matters because it can remove much of the appreciation that occurred during the previous owner’s lifetime from the heir’s gain calculation. Suppose a parent bought a Utah home decades ago for $120,000, but it was worth $500,000 on the date of death. If the inherited basis is $500,000 and the heir later sells near that amount, the gain may be small even though the home increased greatly in value during the parent’s ownership.
The basis of inherited property can become more complicated when ownership was shared, the estate uses an alternate valuation date, or prior transfers affect basis. Keep the estate and ownership records rather than assuming the date of death value is always the only number needed.
Why a Date of Death Appraisal Matters
Reliable evidence of fair market value inherited property had on the date of death can be important because that value may become the starting basis for the later sale. A qualified appraisal for inherited property tax purposes can provide documented support when the value is not obvious.
The valuation affects the gain or loss calculation, so keep the appraisal, comparable sales analysis, estate inventory, and other records used to establish the number. If the property is sold much later, those records may be harder to recreate.
How to Calculate Capital Gains on an Inherited Property
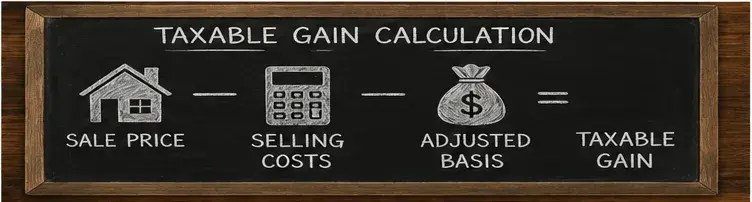
A simple starting formula is: sale proceeds minus eligible selling costs minus adjusted inherited basis equals capital gain or loss. This is only a planning formula. The tax return may require additional adjustments based on the property and taxpayer.
Example: an inherited Utah home has a date of death value of $450,000. The heir later makes $20,000 of qualifying capital improvements, creating an adjusted basis of $470,000. The home sells for $520,000 and eligible selling costs are $30,000. The simplified amount realized is $490,000. Subtracting the $470,000 adjusted basis leaves an estimated $20,000 gain.
This example shows how to calculate capital gains on inherited property without using the deceased owner’s original purchase price as the starting point. Inherited capital assets are generally treated as long term for federal tax purposes regardless of how long the beneficiary held them. The exact capital gains tax on inherited property depends on the taxpayer’s return and other facts.
What Happens If You Sell the Inherited Home at a Loss?
Selling inherited property at a loss can create a capital loss when the sale result is below the adjusted inherited basis, but deductibility is not automatic. The tax treatment can depend on whether the home was held for investment, used personally, rented, or occupied by a beneficiary.
A capital loss on inherited property held for investment may receive different treatment from a loss on a personal use home. If the property was occupied or used in more than one way after inheritance, ask a tax professional how the loss should be treated before assuming it is deductible.
Is the Sale of an Inherited Property Taxable Income?
The gross sale proceeds can be reportable, but tax is generally determined from the gain after basis and applicable adjustments are considered. In other words, receiving $500,000 at closing does not automatically mean $500,000 is taxable gain.
If you are asking is sale of inherited property taxable income, separate the amount received from the profit recognized for tax purposes. The inheritance itself and a later sale are different events. Whether you pay capital gains tax on inherited property depends on the basis, selling costs, sale price, and other tax rules that apply to your situation.
Which Tax Forms May Be Involved After the Sale?
A real estate closing can generate documents that later matter for tax reporting. Form 1099-S is used to report proceeds from many real estate transactions. The sale of inherited property 1099-S reporting does not by itself tell you the taxable gain because the form generally reports gross proceeds rather than your basis.
When reporting is required, Form 8949 inherited property reporting and Schedule D are commonly used for capital asset sales. Keep the closing statement, basis records, appraisal, improvement receipts, and any Form 1099-S you receive. The correct filing treatment depends on the taxpayer and transaction, so use the current IRS instructions or professional tax advice rather than relying on an old form example.
Can You Avoid or Reduce Capital Gains Tax on an Inherited Property?
There is no strategy that guarantees zero tax, but accurate records can prevent you from overstating the gain. The stepped up basis may already reduce the amount substantially. Properly documented capital improvements can increase adjusted basis when tax rules allow, and eligible selling costs may reduce the amount realized.
People searching how to avoid capital gains tax on inherited property should also consider how the property is used before the sale. Moving into the home, renting it, making major improvements, or holding it for several years can change the analysis. These choices should be evaluated for their actual financial purpose rather than made only for a hoped for tax result.
Records to Gather Before Selling an Inherited Home in Utah
Organized records make it easier to estimate taxes and answer questions from a CPA or tax preparer. Gather:
- Death certificate or estate records that establish the inheritance and relevant dates.
- Date of death appraisal or other reliable valuation evidence.
- Estate or probate inventory records when available.
- Receipts for qualifying capital improvements made after inheritance.
- Prior property and ownership records that may affect basis.
- The sale closing statement and records of selling expenses.
- Any Form 1099-S or other tax documents received after closing.
If several heirs share the property, keep copies in one place so the basis and sale records used by each person are consistent.
When Should You Speak With a Tax Professional?
Professional review is especially useful when there are multiple heirs, prior rental use, major improvements, an unclear basis, a trust, an estate tax filing, a large gain, prior gifts involving the home, or unusual ownership history. These facts can affect both basis and reporting.
This article provides general information, not individual tax or legal advice. A CPA, enrolled agent, or tax attorney can apply current federal and Utah rules to the actual estate, ownership history, and tax return.
Frequently Asked Questions
Do I pay capital gains tax on inherited property in Utah?
Possibly. Tax generally depends on whether the sale creates a gain after the inherited basis, selling costs, and other adjustments are considered. A sale near the date of death value may produce little gain, while a property that appreciates after inheritance can create a larger taxable amount.
Does Utah have an inheritance tax?
No. Utah’s former inheritance tax was eliminated after December 31, 2004. Federal estate tax rules are separate, and a later sale of inherited property can still create federal and Utah income tax consequences.
Does Utah have an estate tax?
Utah does not currently impose a separate state estate tax system. Federal estate tax is different and may apply to certain estates. The tax due on a later home sale is a separate capital gain question.
What value is used for an inherited home for tax purposes?
The basis is generally the fair market value on the date of death, subject to exceptions and an elected alternate valuation date in qualifying estate situations. Reliable valuation records are important because the basis affects the later gain or loss.
What if I sell the inherited house for less than its inherited value?
A loss may result, but whether it is deductible depends on how the property was held and used. An investment property can be treated differently from a personal use residence, so review the facts before claiming a deduction.
Will I receive Form 1099-S after selling an inherited property?
Form 1099-S is used for many real estate sales, but whether one is issued can depend on the transaction and reporting rules. If you receive it, keep it with the closing statement and basis records for tax preparation.
Final Takeaway for Utah Heirs Selling a Home
The main tax questions are easier to manage when you separate inheritance from the later sale. Utah does not currently impose an inheritance tax, the inherited basis is generally tied to fair market value at death, and a later sale can create a federal and Utah taxable gain or loss. Before estimating capital gains tax on inherited property, gather the date of death valuation, improvement records, and closing documents. A tax professional can then apply the current rules to your actual numbers before you file.